

Do I go see the doctor, because I’m wicked sick, or do we eat dinner tonight, or do we heat the house?

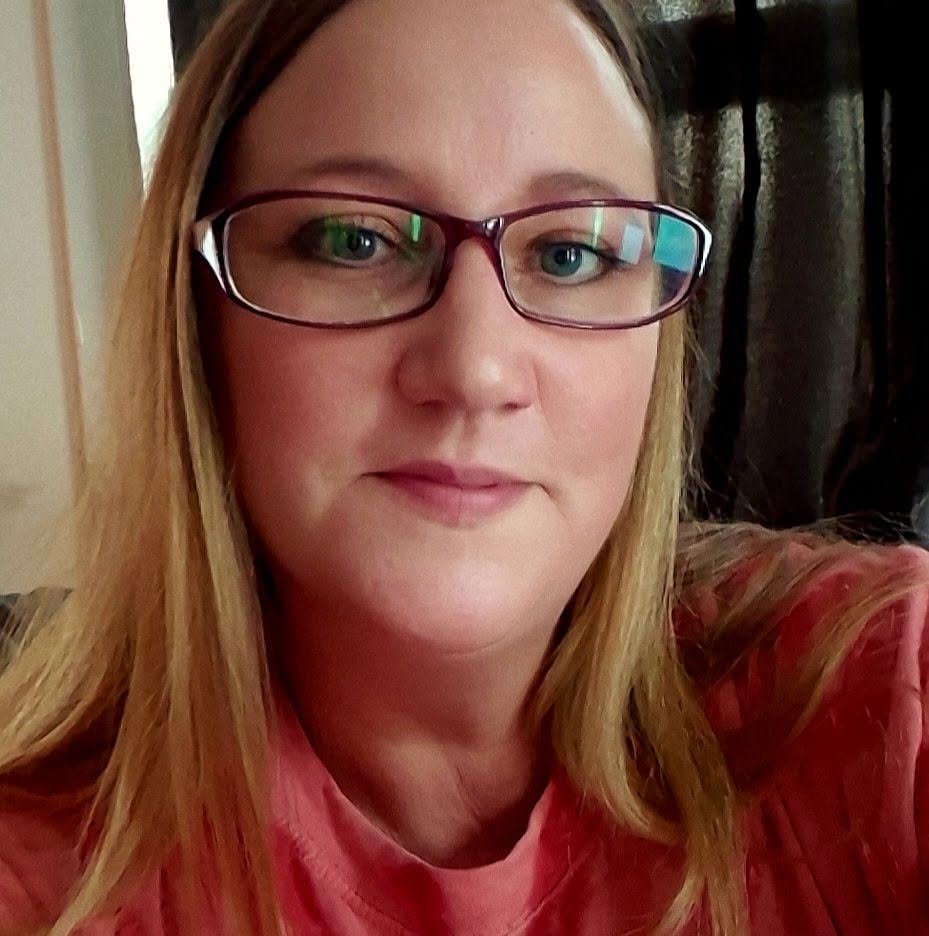
46-year-old Erin Wolfanger is a single mother and full-time social worker in China, Maine. For about the last 10 years, she has had health insurance through her employer. “It feels like every few years they’re switching insurance companies, which can kind of be a nightmare, because with each change comes new policies, new deductibles, new deductions and amounts that I’m paying,” she said.
The most recent switch came in July, when her employer moved to a company called Imagine360. Before she could accept the insurance, Erin had to call and confirm that MaineGeneral, the network where she receives her medical care, would take it. “I was one of the lucky ones and MaineGeneral does accept the insurance, which that was a relief, because that’s all I have access to around here and if they didn’t take my insurance, what would I have done?” she said.
Erin pays close to $200 a month through biweekly paycheck deductions for the highest deductible plan her employer offers, with a $5,000 deductible. Only preventive care is fully covered. “It’s kind of a joke, if I’m being honest with you,” she said.
Erin manages genetic high cholesterol and GERD with prescription medication, and she recently went in for a physical. The visit was covered, but the lab work and additional testing her providers wanted must be paid out of pocket until she reaches her deductible. “I’m about to get a bill for a bunch of lab work that I don’t even know how much that’s going to be,” she said.
At her previous physical, Erin had asked for a Lyme titer and other tests that aren’t covered under general preventive care. Other concerns that came up during that physical led to a couple of outpatient procedures, and she maxed out her $5,000 deductible. “I don’t have that kind of money, I’m a single mom raising a child by myself with limited income, so coming up with a $5,000 deductible is laughable,” she said. “I had to get on a payment plan with the medical providers and that’s why there was a four-year gap between my last physical to now because it took me four years on this payment plan to pay off that deductible from the last annual physical, so I was like, I can’t go back for another physical even because all of the follow-up stuff is going to be an extra charge and I’m still paying off my physical from four years ago.”
If her doctor’s office is closed, her only options are urgent care or the emergency room, which cost even more. She recalled getting sick once and having no choice but to go to urgent care. Her insurance covered only a little of the visit, and she was charged for a portion of it. “I don’t go to the doctor unless I’m dying because I can’t afford it,” she said. “I have health insurance and it’s unaffordable for me, so I, as somebody who actually is covered, haven’t even been able to take care of my medical needs because I have such a high deductible and I can’t afford it,” she added.
Covering her son through her employer insurance isn’t an option either. “My insurance for myself is way cheaper, but if I add someone else to my policy, it quadruples,” she said. Instead, he is enrolled in CubCare, Maine’s subsidized MaineCare program for children, which costs her about $40 a month for full coverage. “It’s actually good comparatively speaking,” she said.
Keeping him covered has not always been possible. When her son was about four years old, Erin took a different job with slightly higher pay. During her MaineCare review, she learned her income would be about $27 a month too high for him to qualify. “The response that I got from Department of Health and Human Services was to just work less, they told me to cut my hours or to find a job that didn’t pay me as much,” she said. “That’s not a solution nor is that something I want to do. I’m trying to work myself out of being dependent on the system.”
She couldn’t afford to add him to her own policy, and her son went without insurance for about six months. “Thankfully in that period of time he didn’t need medical care, but if he did, I don’t know what we would have done, it would have been an impossible situation,” she said.
At the time, the child support Erin was supposed to receive was counted as income, even though she never received it consistently. She said that under the Affordable Care Act, child support was no longer counted toward eligibility, and once that took effect, her son qualified again for subsidized MaineCare. He has been covered ever since. “If that stipulation or rule under the Affordable Care Act went away, I would be in big trouble,” she said.
Erin’s family sits right on the edge of income eligibility. They don’t qualify for food stamps or utility assistance, but “by the skin of our teeth, we qualify for him to have that subsidized health care,” she said. Erin herself qualified for MaineCare only while she was pregnant. “The minute I was not pregnant and had a job, they kicked me off it, but luckily, my kiddo has been able to be on it, or else he would not have health insurance, or I would have to uninsure myself so that I could afford to insure him. One of us would go without health insurance,” she said.
She knows the current administration has made recent changes to requirements and eligibility, and she doesn’t yet know whether they will affect her son. “I could get a letter in the mail any day telling me that my kiddo no longer qualifies for insurance, and then I’m back in that same boat I was in years ago, where I either have to cut down my hours or work for less money, or my kid goes without insurance,” she said. “I wouldn’t be surprised if any day now I got a letter in the mail, and then what do we do?”
Her son is almost 17 and has asthma. “He’s got conditions that need to be monitored by doctors,” she said. When he turns 18, he will no longer qualify for subsidized care through her and will have to apply for MaineCare on his own. If he is working full time by then, Erin expects he won’t qualify. “As an 18-year-old who’s just going out into the world, he can’t afford to pay for his own insurance,” she said. Adding him to her policy would mean “we don’t have enough money after those deductions to pay the power bill, or put food on the table,” leaving the family to decide, “do I go see the doctor, because I’m wicked sick, or do we eat dinner tonight, or do we heat the house.”
Erin has a bachelor’s degree and works in what she calls “a well-respected field.” She knows many people are in a harder spot than she is. “If someone like me, who makes decent money, can’t afford things, especially health insurance, what is everybody else doing? Nothing, they’re dying, they’re literally dying, or they’re getting sick, and can’t get the care they need, that could have been preventable,” she said.
Add your voice to help us continue to push for the best health and health care for all.
SHARE YOUR STORY