

I’m like okay; do I not pay my car note and pay this? Do I eat? Do I ignore the rest of my bills and just try to cover this surgery?

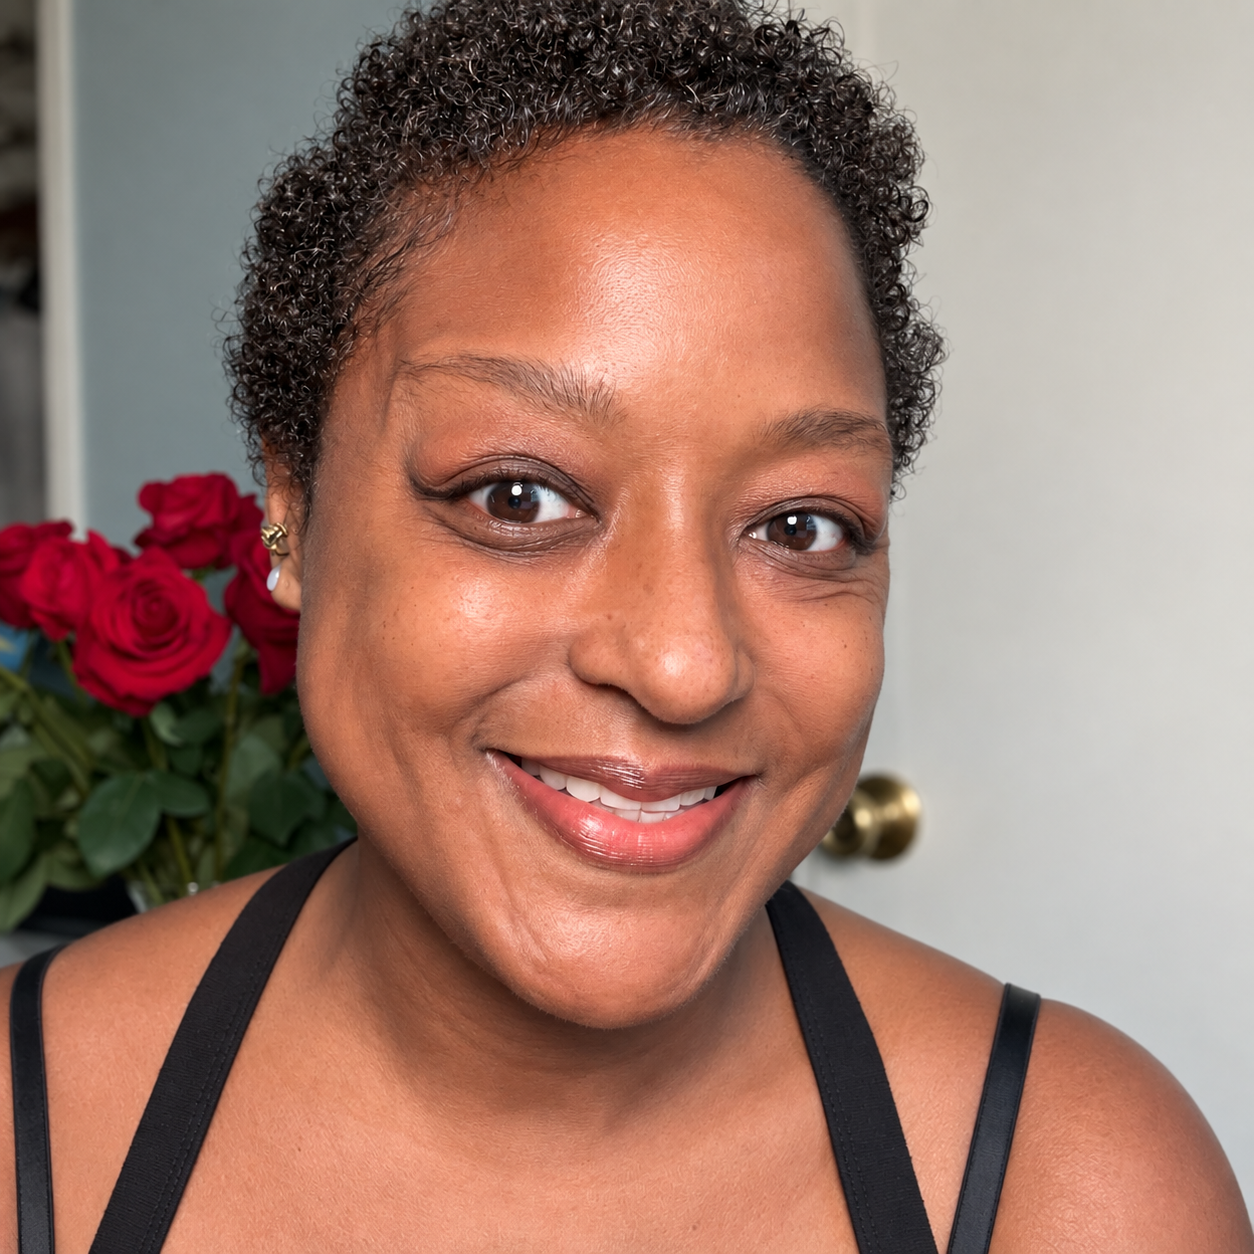
For Regina Dixon, 24 hours made the difference between having health insurance and facing a $28,000 hospital bill.
Her health insurance ended on August 13. The next day, she went to the emergency room.
Doctors found an inflamed gallbladder and gallstones. Regina needed emergency surgery that evening and stayed in the hospital until Sunday.
Just days earlier, Regina had left her job after accepting a new position. She planned to take about a week between jobs to rest and prepare for the transition.
She expected a short break between two jobs, not a gap that could leave her responsible for tens of thousands of dollars in medical bills.
When Regina reviewed her resignation paperwork, she believed she would remain covered for at least part of that time. Her employer had been expected to submit the resignation paperwork the week before, but the paperwork was not processed until August 13, the day her coverage ended.
Regina did not realize her coverage had ended until after she left the hospital.
She discovered something was wrong when several medication receipts from her hospital stay would not go through her flexible spending account. “I was confused because these receipts were from the 14th and so on and I was like what’s going on?”
She called to find out why. “They said, ‘Your plan ended on the 13th,’ literally the day before I went into the hospital,” she said. “I thought I had at least a week or so.”
A few days later, Regina received paperwork about COBRA, which would allow her to continue her former employer’s health insurance. The cost: $814 for one month of coverage.
Her new insurance would not begin until October 1. Regina was told she would need to make the full COBRA payment before the coverage could take effect, though the coverage could then apply retroactively to August 14.
By then, her first hospital bill had arrived.
$28,000.
Regina was now trying to figure out how to come up with $814 while also paying for follow-up care and her regular expenses. “I don’t have just 800 and something dollars laying around the bank,” she said. “I get paid every two weeks… about thirteen hundred dollars every two weeks,” Regina said. “That’s going to be a big chunk of change out of my earnings this month.”
The decision forced Regina to look at her other bills and consider what she could afford to delay. “I’m like okay; do I not pay my car note and pay this? Do I eat? Do I ignore the rest of my bills and just try to cover this surgery?”
She also considered asking the hospital about financial assistance, “Do I try to work something out with the hospital, maybe they have programs or something,” Regina said. “It’s a lot. It’s overwhelming. It’s just stressful.”
Regina ultimately leaned toward paying the COBRA premium. If she could come up with the $814, she expected the coverage to apply retroactively to August 14 and cover the majority of her hospital bills. She would still be responsible for the portion she would have owed under her former insurance, but she would avoid being left to pay the full cost of the hospital bills herself. “If I can somehow get the $814 together and pay it, it’ll go back to the 14th,” she said.
For Regina, paying the premium would mean a greater financial burden in the short term, but potentially less uncertainty about the bills hanging over her. “I think it’s necessary so I can have a little bit more peace of mind and more control over what I’m supposed to be paying,” she said.
But the $28,000 bill was not the only one. Another bill for about $2,300 arrived soon after, and Regina did not immediately know which doctor or service had generated it. “I don’t even know who this is for,” she said. “When you see so many specialists at the same time, everybody is in different practices, I have no idea.”
The bills left Regina frustrated not only by the cost of care, but by how difficult it was to understand what she was being charged for. “How do I verify this?” she said. “It should be itemized and labeled. You should know this charge goes with this doctor and this charge goes with this doctor.”
She said she understood that the hospital, doctors and other providers needed to be paid for their work. What she wanted was a simpler way to keep track of what she owed. “I really wish that everybody would just come together and just send me one big bill,” she said. “Everybody just pulls it in one system.”
Before the emergency surgery, Regina said she had never had much reason to think about what could happen when her employer-sponsored coverage ended. She generally thought about coverage in terms of annual checkups and going to the doctor when she needed to. “It never dawned on me that I would have an emergency like this,” she said.
Now, she approaches health insurance differently.
When Regina enrolled in her new plan, she spent about a week comparing her options, looking closely at premiums, out-of-pocket costs and what each plan covered.
And even though Regina works in property and casualty insurance, she found navigating her own health insurance surprisingly difficult. “It’s very complicated,” she said. “Out of all these plans, it’s challenging to know which one is the most beneficial.”
Regina only wanted a week to get settled before starting her new job. “I just wanted a couple of days to get my desk together and reset,” she said. “I wouldn’t think this would happen to me … who knew that a 24-hour period would have changed so much?”
The experience has made Regina realize just how much can hinge on the details of employer-sponsored insurance when someone changes jobs. The advice she would now give someone preparing to leave a job is simple: “Before any type of position that you decide to leave, check and see how their insurance works after you resign.”
Add your voice to help us continue to push for the best health and health care for all.
SHARE YOUR STORY